
Storage
Server DRAM vs. Mobile DRAM Price Divergence: Arbitrage Opportunity Analysis
The DRAM market is never perfectly synchronized. Even though server DRAM and mobile DRAM share common manufacturing roots, their price trajectories often diverge because each segment is driven by different demand cycles, product mixes, and strategic priorities. When that divergence becomes pronounced, it naturally raises the question: is there an arbitrage opportunity? Can manufacturers, module houses, or even investors exploit pricing gaps between server and mobile DRAM in a systematic way?
Shortages in DDR5 PMIC and SPD Hub Supply Chain
The transition to DDR5 has introduced not only new performance levels for memory systems but also new complexities in the component supply chain. Among the most critical changes are the introduction of on‑DIMM power management ICs (PMICs) and dedicated SPD hubs, both of which are essential for DDR5 modules to function correctly. As demand for DDR5‑based platforms accelerates, shortages in these components have emerged as a key bottleneck, impacting module makers, OEMs, and data center planners alike.
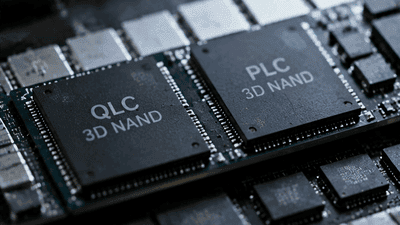
NAND Makers Shift from Production Cuts to QLC/PLC Capacity Allocation
After several years of responding to weak pricing and oversupply with production cuts, NAND flash manufacturers are pivoting to a different playbook. Instead of simply dialing back wafer input, they are reallocating capacity toward higher‑density technologies such as QLC (quad‑level cell) and PLC (penta‑level cell). This strategic shift reflects a maturing market in which the main lever is no longer how many bits to produce, but what kind of bits to make and for which segments.
Memory Inventory Digestion Nearing End, Channel Restocking Intentions Strengthen
As the memory cycle of the early–mid 2020s unfolds, one phrase is increasingly heard in industry discussions: the “inventory digest” is nearing its end. For DRAM and NAND makers, module houses, and downstream OEMs, this signals a turning point from prolonged destocking toward a new phase of restocking and channel “restacking.” At the same time, the strength of that restacking intent—how aggressively the supply chain rebuilds inventory and reshapes product mix—will determine the character of the next leg of the memory cycle, from pricing behavior to technology adoption.
RAID and Erasure Coding Evolution – New Durability Requirements for NAND
As data grows in scale and strategic importance, the mechanisms used to protect it have evolved far beyond traditional disk-era assumptions. RAID, once the primary tool for redundancy and durability, now coexists and competes with erasure coding and other advanced schemes tuned for modern distributed storage. At the same time, NAND flash has become the dominant medium for performance-sensitive storage, bringing its own unique endurance and reliability characteristics.
Structural Changes in Equipment Investment within Memory Chip CapEx
Capital expenditure (CapEx) in the memory industry has always been tightly coupled to equipment investment: lithography scanners, etchers, deposition tools, testers, and packaging lines together define the production capability of DRAM and NAND fabs. Yet, over the last several years, the structure of that equipment investment has changed in ways that reflect deeper shifts in memory technology, demand patterns, and risk management. Instead of simply scaling “more of the same,” memory makers are reallocating CapEx across tool categories, nodes, and geographies, reshaping how future bit supply will be created.
Enterprise NVMe SSD Share Jumps in AI Data Center Procurement Lists
Across the global AI infrastructure landscape, one detail keeps showing up in procurement documents, request‑for‑proposal (RFP) packages, and server bill‑of‑materials: the proportion of enterprise NVMe SSDs is rising sharply. As organizations scale out AI training and inference clusters, they are revisiting every layer of the stack to remove bottlenecks, and storage is no exception. Where traditional SATA SSDs and even high‑end HDDs once dominated, enterprise‑grade NVMe SSDs are now claiming a steadily larger share of the storage line items in AI data center procurement lists.
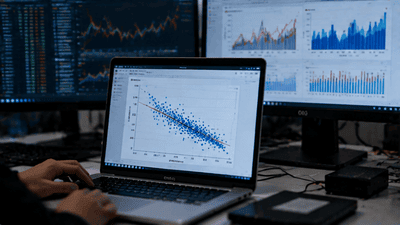
Regression of Data Center SSD Capacity Demand vs. AI Model Size
As AI models grow from millions to billions and now trillions of parameters, data centers are experiencing an equally dramatic expansion in SSD capacity demand. The relationship between how large an AI model is and how much flash storage a data center needs is not linear, but it is systematic enough that architects and planners can model it using regression techniques. Understanding this relationship is crucial for sizing infrastructure, forecasting storage purchases, and ensuring that GPU and accelerator investments are not bottlenecked by inadequate storage capacity.
A Quantitative Estimate of HBM’s Crowding-Out Effect on Traditional DRAM Capacity in 2026
High Bandwidth Memory (HBM) has moved from a niche technology to a central pillar of AI and high‑performance computing in just a few years. As demand for AI accelerators surges, HBM capacity has become one of the most critical and constrained resources in the memory ecosystem. In 2026, this rapid expansion of HBM production is not happening in isolation; it interacts directly with traditional DRAM manufacturing capacity and investment decisions.
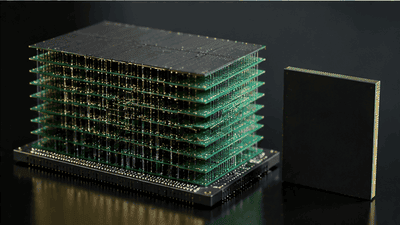
NAND Layer Count Enters 500+ Era: Technology Roadmap and Equipment Demand
The evolution of 3D NAND has been defined by an almost relentless climb in layer count, and the industry is now standing at the threshold of the 500+ layer era. This milestone is more than a numerical achievement; it signals a new phase in how the memory ecosystem thinks about density scaling, process integration, and capital equipment investment.