
The Post-Moore Path for AI Chips: Advanced Packaging Succeeds Process Scaling
For decades, the semiconductor industry rode a remarkably simple storyline: shrink transistors, pack more of them onto a die, and enjoy automatic gains in performance and efficiency. That story—embodied in Moore’s Law—still matters, but for AI chips in the mid‑2020s it is no longer the sole, or even primary, driver of progress.
Global AI Accelerator Market Breaks $250B in 2026: A Supply Chain Teardown
By 2026, AI accelerators have moved from niche hardware to the beating heart of modern compute, powering everything from frontier model training to real‑time inference across clouds, enterprises, and edge devices. Crossing the $250 billion mark in annual market value is not just a milestone; it is a reflection of a vast, intricate supply chain that stretches from design labs and fabs to packaging houses, board makers, system integrators, and the services that wrap around them. Understanding how this value is created and captured requires a teardown of the AI accelerator supply chain, layer by layer.
AI Chip TDP Grows 50% Per Gen, Data Center Power Architecture Faces Reassessment
Over the past several AI chip generations, one trend has become impossible to ignore: thermal design power (TDP) is climbing at a pace that would have seemed extreme even a few years ago. When flagship accelerators and high‑end AI chips see TDP grow on the order of 50% per generation, the consequences extend far beyond chip packaging.
A Quarterly Tracking Framework for Semi Buyback Scale and FCF Yield
Semiconductor stocks sit at the intersection of two moving targets: who is buying them, and what their cash flows are worth in a changing macro environment. In one quarter, large institutions dominate flows and free cash flow (FCF) yields look attractive versus bond yields. In another, retail flows surge, multiples expand, and FCF yields compress as rates rise. If you want to understand where you are in the cycle—not just price, but positioning and valuation—you need a framework that connects buyer scale and FCF yield to the macro levers of interest rates, exchange rates, credit, and commodities.
Cyclical Pricing Power Shifts Reflected by the HHI Industry Concentration Index for Memory
Pricing power in the memory sector does not move in a straight line. It ebbs and flows with cycles of demand, supply, consolidation, and technological transition. At the same time, the industry’s structure — who holds how much market share — is not static either. One of the most useful ways to capture this structure is the Herfindahl-Hirschman Index (HHI), a simple but powerful concentration metric that can reveal how much leverage the leading players have at any given moment.
Thematic ETFs
Record New Launches of Memory/AI Thematic ETFs in 2026 – Capital Siphoning Effects
Thematic ETFs
2026 Investor Structure Shifts in Memory Thematic ETFs – Retail Out, Institutions In
Thematic ETFs
A High-Frequency Leading Indicator Model Linking Memory Indices and PC/Smartphone Shipments
Thematic ETFs
Overweight/Underweight Execution via Memory Thematic ETFs in Sector Rotation
Thematic ETFs
Macro Cycle
Intensifying Semi Sector Divergence: The Trilogy of Analog, Digital, and Power
R&D Intensity Ranking in Semis: Who Keeps Doubling Down on the Future?
Interpreting the Sentiment Signal as Wafer Fab Utilization Breaches 85%
Japan’s Semi Renaissance: Joint 2nm R&D Progress Among 8 Major Giants
Practical Application of the Inventory-to-Bill Ratio in Semi Industry
Semi Inventory Days Drop Below 90, Restocking Cycle Officially Begins
Storage
Memory Inventory Digestion Nearing End, Channel Restocking Intentions Strengthen
As the memory cycle of the early–mid 2020s unfolds, one phrase is increasingly heard in industry discussions: the “inventory digest” is nearing its end. For DRAM and NAND makers, module houses, and downstream OEMs, this signals a turning point from prolonged destocking toward a new phase of restocking and channel “restacking.” At the same time, the strength of that restacking intent—how aggressively the supply chain rebuilds inventory and reshapes product mix—will determine the character of the next leg of the memory cycle, from pricing behavior to technology adoption.
Shortages in DDR5 PMIC and SPD Hub Supply Chain
The transition to DDR5 has introduced not only new performance levels for memory systems but also new complexities in the component supply chain. Among the most critical changes are the introduction of on‑DIMM power management ICs (PMICs) and dedicated SPD hubs, both of which are essential for DDR5 modules to function correctly. As demand for DDR5‑based platforms accelerates, shortages in these components have emerged as a key bottleneck, impacting module makers, OEMs, and data center planners alike.
RAID and Erasure Coding Evolution – New Durability Requirements for NAND
As data grows in scale and strategic importance, the mechanisms used to protect it have evolved far beyond traditional disk-era assumptions. RAID, once the primary tool for redundancy and durability, now coexists and competes with erasure coding and other advanced schemes tuned for modern distributed storage. At the same time, NAND flash has become the dominant medium for performance-sensitive storage, bringing its own unique endurance and reliability characteristics.
Enterprise NVMe SSD Share Jumps in AI Data Center Procurement Lists
Across the global AI infrastructure landscape, one detail keeps showing up in procurement documents, request‑for‑proposal (RFP) packages, and server bill‑of‑materials: the proportion of enterprise NVMe SSDs is rising sharply. As organizations scale out AI training and inference clusters, they are revisiting every layer of the stack to remove bottlenecks, and storage is no exception. Where traditional SATA SSDs and even high‑end HDDs once dominated, enterprise‑grade NVMe SSDs are now claiming a steadily larger share of the storage line items in AI data center procurement lists.
Advanced Packaging
Macro Linkages
Quarterly Changes in Global Systemically Important Banks’ Credit Policies for Semis
Macro Linkages
The Chain Reaction of BOJ Rate Hikes on Yen Financing Costs for Equipment Giants
Macro Linkages
The Inverse Relationship Between Mutual Funds’ Overweight Ratio in Semis and Forward Returns
Macro Linkages
Synchronicity Regression Test Between Global Manufacturing PMI and Semi Orders
Macro Linkages
HBM Memory
Incremental Demand for HBM Test and Burn-in Equipment – A Quantified Forecast
HBM’s Value Share Per AI Server Unit Continues to Rise
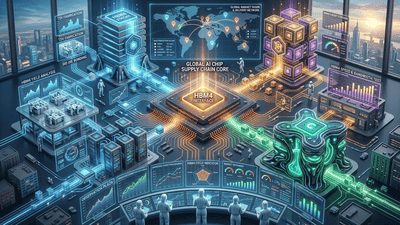
HBM4 Mass Production Kickoff: The 2026 Tech Roadmap Showdown Among 3 Memory Giants
TSV Technology Iteration in HBM – New Requirements for Equipment Suppliers
The Dual Impact of HBM Reliability Test Standard Upgrades on Yield and Cost
Global HBM Patent Landscape Competition: The US-China-Japan-Korea Power Game
ETFs
Market Sentiment Revealed by Changes in Semi ETF PCF Baskets
If you spend any time in the semiconductor space, you quickly realize that prices do not move only on earnings calls and product launches. They also move on flows, on mechanics, on the quiet, daily processes that keep exchange-traded funds running. One of the most important of those processes is the construction of the Portfolio Composition File, or PCF – the basket that authorized participants use to create and redeem ETF shares. When we talk about semi-themed ETFs, the evolution of those PCF baskets can be a surprisingly rich source of information about what the market is really thinking.
Correlation Matrix and Diversification Benefits of US vs. A-Share Semi ETFs
Semiconductor ETFs are often treated as if they all tell the same story, but that is not quite true. A U.S. semiconductor ETF and an A-share semiconductor ETF may both be linked to the chip cycle, yet the way they behave in a portfolio can be very different. That difference shows up clearly in a correlation matrix. Once you compare the two side by side, you can start to see whether they actually diversify each other or whether they simply move together in disguise.
The Pricing Impact of SOXX’s Portfolio Changes on Individual Constituents
Semiconductor-themed ETFs have become a go-to vehicle for investors who want exposure to chips, equipment makers and the broader AI hardware ecosystem without betting on a single stock. Among them, the iShares Semiconductor ETF, ticker SOXX, is one of the bellwethers of the space, closely watched by both retail traders and institutional desks for what its moves may signal about the sector as a whole. When SOXX changes its portfolio – whether through scheduled rebalancing or more tactical adjustments – the ripple effects can be felt not only in the ETF’s own price, but in the pricing of its individual constituents as well.
Lead-Lag Relationship Between Global Semi ETF Flows and Korea Semi Export Data
The relationship between global semiconductor ETF flows and Korea’s semiconductor export data is a useful way to understand how market sentiment and real-world trade fundamentals interact. One side of the story is financial: money moving into and out of semiconductor ETFs around the world. The other side is industrial: the actual shipment of chips and chip-related products from one of the world’s most important semiconductor exporters. Put those together, and you get a compelling question. Do ETF flows lead Korea’s export data, or do exports lead ETF flows? The answer is not always the same, and that is what makes the relationship worth studying.